💰 The Power of Savings Goals: How to Save with Purpose and Grow with Confidence
Most people agree that saving money is important—but why you’re saving matters just as much as how much you save. That’s where savings goals come in.
Having clear, defined savings goals turns vague intentions into real, achievable outcomes. Whether it’s building an emergency fund, putting down a deposit on a home, or planning a holiday, setting the right goals keeps you focused, motivated, and in control of your financial journey.
🎯 Why Are Savings Goals So Important?
- They Give Your Money Purpose
Without a goal, it’s easy to spend whatever is left in your account. Goals give direction to your money and help you make conscious decisions about how to use it. - They Keep You Accountable
When you know what you’re saving for, you’re more likely to stick to your plan—even when temptation strikes. - They Reduce Financial Stress
Having money set aside for specific goals brings peace of mind, knowing you’re prepared for the expected and the unexpected. - They Empower Better Habits
Savings goals help develop discipline, consistency, and delayed gratification—all of which strengthen your long-term financial health.
🏗️ How to Set and Achieve Your Savings Goals
Here’s a simple framework to help you succeed:
1. Define the Goal
Be specific. “Save more” is vague. “Save R20,000 for a December holiday” is actionable.
2. Attach a Timeline
Set a realistic deadline. This helps you calculate how much to save each week or month.
3. Break it Down
Divide the goal by your time horizon to create smaller, manageable monthly targets.
(Example: R20,000 in 10 months = R2,000/month)
4. Automate Your Savings
Set up a scheduled transfer into a dedicated savings account the moment your income comes in.
5. Track and Review
Check in monthly to see if you’re on track. Adjust your plan if your circumstances change.
6. Celebrate Milestones
Reaching a goal—even a small one—is worth celebrating. It reinforces the habit and keeps motivation high.
💡 Saving vs. Investing: What’s the Difference?
While both are essential to your financial health, saving and investing serve different purposes.
| Saving | Investing |
|---|---|
| Short- to medium-term | Medium- to long-term |
| Low or no risk | Involves market risk |
| Typically in a bank or money market account | In assets like shares, unit trusts, ETFs |
| Preserves capital | Aims to grow capital |
| Best for emergencies or planned expenses | Best for retirement, wealth creation, long-term growth |
👉 Rule of Thumb:
- Save for goals you want to reach within 1–3 years.
- Invest for goals 3+ years out, where you can weather short-term market movements.
Your first priority is building a solid savings base—this includes:
- Emergency fund (3–6 months of expenses)
- Short-term goals (travel, appliances, education)
- Cash buffer for peace of mind
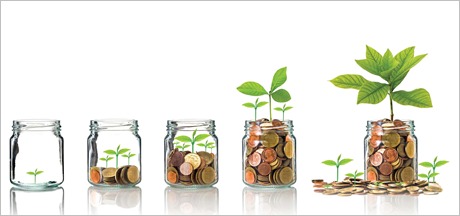
Once your savings goals are in place, you can start directing surplus income towards investments—where your money works harder over time, building wealth through growth, dividends, and compounding returns.
🚀 Final Thoughts
Having savings goals is not just about being disciplined—it’s about being intentional with your money. It’s about taking control of your future, one goal at a time.
And remember: saving gets you started, investing takes you further.
If you need help identifying your goals or choosing the right mix between saving and investing, speak to a qualified financial advisor or reach out to our team—we’re here to help.
Need help getting started?
Reach out to a Mentorfin coach for personalised savings and investment coaching that aligns your goals with smart financial strategies.